What Beneficiaries Should Know About Coverage Options and Enrollment Deadlines
If you received a notice last fall that your Medicare Advantage plan would not be available in 2026, you were among a large group of beneficiaries affected by a notable shift in the Medicare Advantage market.
Research published in the medical journal JAMA found that approximately 10% of Medicare Advantage (MA) enrollees nationwide had their plans discontinued for 2026, resulting in nearly 2.9 million people needing to find new coverage. For context, disenrollment rates averaged around 1% annually from 2018 through 2024, before rising to nearly 7% in 2025 and reaching 10% this year, according to research led by Dr. Mark K. Meiselbach of the Johns Hopkins Bloomberg School of Public Health.
The impact has varied considerably by state. In Vermont, more than 90% of MA enrollees received non-renewal notices. Wyoming, South Dakota, and New Hampshire were also among the states with larger shares of affected beneficiaries. Rural areas and regions with higher-cost populations have generally seen more plan exits than other parts of the country.
Why Are Some Plans Leaving the Market?
Several factors appear to be contributing to plan exits, and different stakeholders point to different causes.
Insurers have cited rising medical costs as a primary driver. One contributing factor is that many patients who delayed care during the COVID-19 pandemic have since sought that care, increasing utilization and costs. The cost of treatment has also risen broadly.
At the same time, some policymakers and researchers argue that federal payment rates to MA plans have historically been higher than what it would cost to cover the same beneficiaries under Original Medicare — and that recent regulatory steps to adjust those payments are a necessary correction. Insurers counter that the adjustments have not kept pace with their actual costs, making some markets difficult to operate in profitably.
Both perspectives are part of an ongoing policy debate. What is clear from the data is that carriers — particularly smaller insurers — have been pulling back from certain markets, and some larger carriers have also reduced plan offerings or benefits in specific areas.
What Happens When a Plan Is Discontinued?
When a Medicare Advantage plan stops participating in Medicare, coverage under that plan ends on December 31 of that year. According to the Medicare & You 2026 Handbook, your plan is required to send you a letter explaining your options.
One practical consideration when switching plans is that MA plans operate with their own provider networks and drug formularies, both of which can differ significantly from one plan to another. Depending on the new plan you select, your current doctors or specialists may or may not be in-network, and your prescription drugs may be covered differently — either in terms of whether they are covered at all or what cost tier they fall into.
Reviewing these details carefully before selecting a new plan can help minimize disruption to your care.
Coverage Options to Consider
Beneficiaries whose plans were discontinued generally have three main paths available. Each has its own structure, costs, and trade-offs.
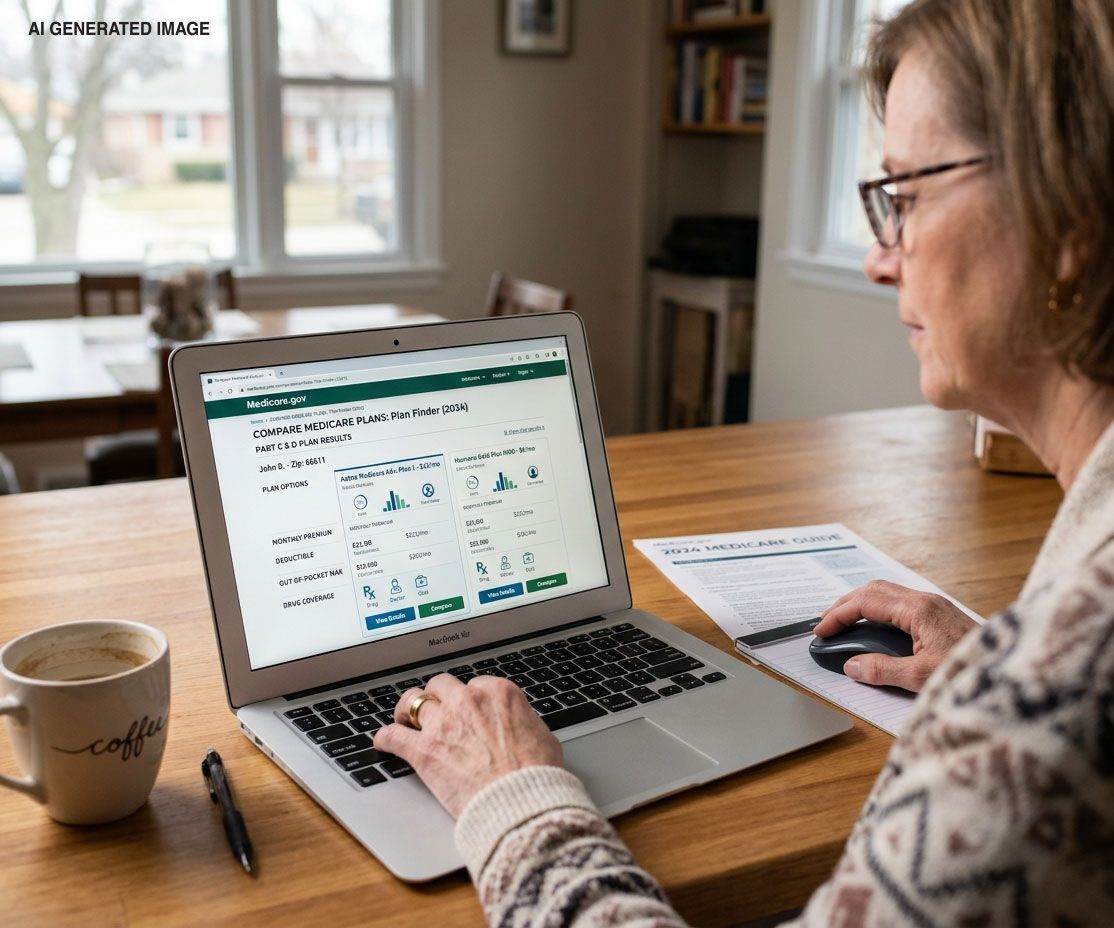
Enroll in a different Medicare Advantage plan. You may be able to find another MA plan in your area that meets your needs. When comparing plans, it is worth checking whether your current providers are in the plan's network, whether your medications are on the plan's formulary and at what cost tier, differences in copayments and coinsurance from your current plan, and differences in supplemental benefit coverage such as gym memberships, transportation, and dental and vision benefits. Medicare's Plan Finder tool at Medicare.gov/plan-compare allows you to compare plans available in your area.
Return to Original Medicare (Parts A and B). Original Medicare is not tied to provider networks, which means you can generally see any doctor or specialist who accepts Medicare. However, Original Medicare does not include an out-of-pocket maximum, so you may be responsible for deductibles and coinsurance costs without a cap. Many people who return to Original Medicare also enroll in a stand-alone Medicare drug plan (Part D) to help cover prescription costs.
Purchase a Medicare Supplement (Medigap) policy. Medigap policies are sold by private insurers and are designed to work alongside Original Medicare, helping to cover costs such as deductibles, coinsurance, and copayments. Medigap plans carry a monthly premium in addition to the Part B premium, but they can provide more predictable out-of-pocket costs. Coverage and pricing vary by plan type and insurer.
Guaranteed Issue Rights: A Time-Sensitive Consideration
One important protection that applies when a Medicare Advantage plan is discontinued is the right to purchase certain Medigap policies without medical underwriting. Under federal law, insurance companies generally cannot deny you a Medigap policy, charge higher premiums based on pre-existing conditions, or impose pre-existing condition waiting periods during a guaranteed issue period.
According to the Medicare & You 2026 Handbook, if your plan stops participating in Medicare, you may have the right under federal law to buy certain Medigap policies within
63 days after your plan coverage ends. Depending on your state, additional rights may also apply.
This window is defined by federal (and in some cases state) law. If you are considering a Medigap policy following a plan discontinuation, it is worth understanding when your guaranteed issue rights apply and for how long, so you can make decisions within the applicable timeframe.
Enrollment Periods to Be Aware Of
Beyond the guaranteed issue window, there are several enrollment periods that may be relevant depending on your situation.
The
Annual Enrollment Period runs October 15 through December 7 each year. During this period, you can join, switch, or drop a Medicare Advantage plan or Medicare drug plan, with coverage changes taking effect January 1. Your plan is required to send you an Annual Notice of Change by September 30, which outlines any upcoming changes to costs, coverage, or networks.
The
Medicare Advantage Open Enrollment Period runs January 1 through March 31. If you are currently enrolled in a Medicare Advantage plan, you can use this period to switch to a different MA plan or return to Original Medicare. This period does not allow you to move from Original Medicare into a Medicare Advantage plan.
If you are unsure which enrollment periods apply to your situation, your State Health Insurance Assistance Program (SHIP) provides free, unbiased counseling to Medicare beneficiaries. A licensed insurance broker who specializes in Medicare may also be a helpful resource for comparing your options.
Looking Ahead
Medicare Advantage remains a significant part of the Medicare landscape, and the market continues to evolve. Plan availability, provider networks, benefits, and costs can change from year to year, which makes an annual review of your coverage a worthwhile habit regardless of whether your plan has been affected by recent market changes.
Understanding your options — and the timeframes associated with them — puts you in a better position to choose coverage that fits your health needs and financial situation.